Fifth Third: 53 Mobile Banking

Screenshots
Details
- Rating
- 34.94K reviews
- Version
- 5.26.0
- Developer
- Fifth Third Bank
Analysis by Norviv
When I first opened Fifth Third: 53 Mobile Banking, I approached it as a practical tool rather than something I would spend time exploring. That is the right mindset for this Finance app from Fifth Third Bank: it is designed to help customers handle everyday banking from a phone, without treating mobile banking like a complicated financial dashboard. The central appeal is simple—your account is available when you need it, even outside branch hours.
The app is free, aimed at Everyone, and has been available since November 16, 2011. Its long presence on mobile is reflected in the way it feels focused on routine tasks instead of trying to become an all-purpose money-management platform. With a 4.7 average from around 217 thousand ratings and over 1 million installs, it is clearly familiar to a large number of Fifth Third customers.
My main advice to a first-time user is to define success before installing it. If your goal is to check an account, review recent activity, or manage a normal banking task from your phone, this is the kind of app that can make that process less disruptive. If you want a bank-independent budgeting system, investment research, or a broad comparison of multiple financial institutions, you will probably need a different tool alongside it.
Getting comfortable with the mobile banking experience
The first thing to understand is that this is a bank-specific app, not a general finance organizer. That distinction affects nearly every decision you make inside it. The developer is Fifth Third Bank, so the most natural experience is for someone who already banks with Fifth Third and wants a direct mobile connection to that relationship.
I find that approach useful because it reduces the clutter found in apps that combine accounts from many institutions. You are not opening the app to build a complete picture of every credit card, savings product, loan, and investment you may have elsewhere. You are opening it to deal with Fifth Third banking in the moment. That narrower purpose can be a strength when you are standing in a checkout line and need to verify something quickly.
There is also a trade-off. A focused banking app does not replace the broader view offered by a dedicated budgeting service or a spreadsheet. If you divide your finances between several banks, the app will not automatically become your single source of truth for every account. I would use it for direct account access and pair it with another method for long-term planning if that is important to you.
The current version is 5.26.0, and it supports devices running iOS 9 or later. That makes checking your phone’s operating system a sensible first step, especially if you are using an older device. Compatibility is easy to overlook when an app is free, but it is frustrating to complete a download attempt only to discover that the phone needs an update or is no longer suitable.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
The store summary, “If your phone is on, your bank is open,” captures the convenience better than a list of features would. I would interpret it as access to banking when the branch is closed, not as a promise that every banking situation can be solved instantly from the screen. Some requests still require careful review, additional verification, or direct contact with the bank.
What to prepare before installing
For a smoother start, I would have my Fifth Third account information and the phone I normally use ready before opening the app. I would also make sure I can receive any account-related verification required during sign-in. This is not a glamorous tip, but it prevents the most common first-session failure: reaching the login step and then having to search for information or switch devices.
I would avoid installing it while rushing to make a payment or while standing somewhere with an unreliable connection. A first login is the wrong moment to experiment. Give yourself a few quiet minutes, read each prompt, and confirm that you are using the official Fifth Third banking application rather than relying on a similarly named result.
Because this is a financial app, I would also treat the phone itself as part of the security routine. Use a device you control, keep its operating system maintained, and do not hand an unlocked phone to somebody else after signing in. These habits matter more than cosmetic customization, particularly when the app gives you access to real account information.
From installation to the first useful result
After installation, the meaningful path is straightforward: open the app, sign in through the Fifth Third account process, and look for the information that answers your immediate question. For most new users, that first question is likely to be whether a transaction has posted or how much money is currently available. I recommend starting there rather than tapping through every screen.
That first check is valuable because it confirms several things at once. You learn whether your credentials work, whether the account you expected is visible, and whether the app’s presentation makes sense to you. If the balance or activity does not look familiar, pause before taking action. Compare the displayed information with what you already know instead of assuming that a confusing screen means something is wrong with the account.
My preferred first-session workflow is deliberately small. I sign in, review the newest activity, identify one transaction I recognize, and then close the app. That gives me confidence without encouraging unnecessary changes. Once I know the basic path, I can return later when I actually need to manage something.
A useful habit is to separate checking from acting. Looking at recent activity is low pressure; moving money or making another account change deserves a second look. Before confirming any important action, I would verify the selected account, the destination, the amount, and the date shown on screen. A banking app can make a task feel quick, but quick should not mean automatic.
A realistic everyday scenario
Imagine that I am leaving a grocery store and cannot remember whether a recent purchase has already appeared in my account. Instead of waiting until I get home to open a laptop, I launch the app, sign in, and review the latest activity. If the transaction is present, I can reconcile it with my receipt and move on. If it is not there, I know not to treat the missing entry as proof that the purchase disappeared; posting and timing can make account activity less immediate than the moment a card is used.
This is where the app feels most useful to me. It turns a small uncertainty into a quick check without requiring a branch visit. The benefit is not that it makes financial decisions for me. The benefit is that it puts current account information close enough to use while the question is still relevant.
Another practical use is checking an account before a scheduled expense. I would review recent activity first, then consider the available balance and the payments I already know are coming. The app can support that decision, but I would not confuse a displayed balance with a complete forecast of my month. For a full cash-flow plan, I still prefer writing down upcoming bills and irregular expenses separately.
Where first-time users can become confused
The most likely confusion is expecting every banking term to match everyday language. “Balance,” “available,” “pending,” and “posted” can describe different stages of account activity, and a new user may read them as interchangeable. My advice is to slow down whenever a transaction is recent or the amount seems unexpected. Read the labels around the figure instead of relying on the largest number on the screen.
Another point of friction is assuming that seeing an account means every related task is available in exactly the same place. Bank apps often organize viewing and management separately, so I would follow the wording on each screen carefully. If a button does not appear where you expect it, that does not necessarily mean the account is missing or damaged; it may simply be located under a different section or require another step.
Login trouble is another reason to avoid testing the app during an emergency. If your credentials are rejected, do not repeatedly guess. Use the account recovery route presented by the app or contact Fifth Third through an official channel. I would never send banking details to someone who contacts me unexpectedly claiming to offer help with the app.
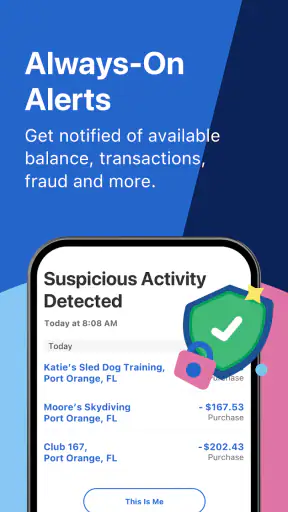
Notifications can also create a false sense of completeness. An alert may draw attention to an event, but I still prefer opening the account view when I need the full context. A short notification is useful for awareness; it is not always enough for deciding what to do next.
Finally, remember that a mobile banking screen is not the same as a personal finance report. It may show what you need for a current decision, while leaving you to interpret recurring charges, shared household expenses, or money held elsewhere. That is not a defect so much as a boundary. Understanding the boundary prevents disappointment.
Using it alongside other financial tools
Compared with visiting a branch, the app wins on convenience and timing. I can check information without arranging my day around opening hours, and I do not need a desktop computer for a simple question. Compared with a bank website in a mobile browser, a dedicated app usually feels more direct because it is built around repeated phone use rather than a page designed for a larger screen.
Compared with an independent budgeting app, the advantage is directness. A Fifth Third app is the place I would go for Fifth Third account information, while a budgeting service is more useful when I want categories, cross-bank totals, spending trends, or a wider household view. The alternative is better for analysis; this app is better for the source account itself.
That difference affects who should skip it. I would not choose this as my main financial app if I do not bank with Fifth Third, if I need detailed investment tools, or if my priority is combining accounts from several institutions into one planning workspace. I would also avoid relying on it alone if I need a carefully structured monthly budget. In those cases, the app may still be useful for one account, but it is not the complete solution.
For an existing Fifth Third customer who mainly wants mobile access, the narrower scope is reasonable. The app’s 35 thousand reviews and broad user base suggest that it has become a familiar part of many customers’ banking routines, although popularity should not replace checking whether its workflow fits your own needs.
Small habits that make the experience better
My first tip is to decide what you are checking before opening the app. “I need to confirm one purchase” is better than wandering through financial information without a purpose. It keeps the session short and makes it easier to notice something that genuinely needs attention.
My second tip is to review activity in context. When a charge looks unfamiliar, compare the amount and timing with receipts, subscriptions, household purchases, or a merchant’s alternate billing name before reacting. This does not mean ignoring suspicious activity; it means gathering enough context to distinguish a recognizable transaction from one that deserves prompt action.
My third tip is to use a two-pass approach for important actions. On the first pass, enter the details. On the second, stop and verify the account and amount before confirming. That extra pause is especially worthwhile when you are tired, multitasking, or using a small screen.
My fourth tip is to keep a separate note of planned bills if you are using the app to manage your month. The app can help you see what has happened, but a simple list can remind you what has not happened yet. Combining those two views gives me a more reliable picture than either one alone.
My fifth tip is to treat the app as a private doorway, not a public convenience. I would avoid signing in on a borrowed phone, leave the app when finished, and be cautious with messages that ask me to “verify” banking information outside the normal app experience. Convenience is valuable only when paired with attention.
Who will get the most from it
I think this app is best for a Fifth Third customer who wants a dependable mobile routine: open the app, sign in, check activity, confirm an account detail, and handle an ordinary banking need without waiting for a branch. It is also a good fit for someone who prefers a bank’s own app over connecting financial information to a separate service.
It may be less satisfying for a person who wants coaching, detailed spending visualizations, or a single dashboard covering many banks. Those users should consider a broader finance application as a companion rather than expecting this one to provide every planning feature. The right choice depends on whether your priority is direct access or analysis across your whole financial life.
The Everyone age rating makes the app approachable in terms of store classification, but I would still treat it as an adult financial tool in practice. Anyone using it should understand the account actions they are taking and should have a safe way to manage login information. A simple interface does not remove the need for responsible decisions.
My recommendation after regular use
After looking at it as a first-time customer would, I see Fifth Third: 53 Mobile Banking as a focused utility with a clear purpose. It is not trying to replace a budget planner or become an investment workstation. Its value comes from putting Fifth Third banking within reach when a quick account check or routine task matters.
I like the app most when I use it with a narrow question and a careful final review. That approach makes the first successful action reassuring: sign in, find the relevant account, understand the activity, and finish without unnecessary exploration. The main limitations are equally clear: the experience is tied to Fifth Third, and users who want broad financial analysis will need another tool.
For an existing customer, the free price removes the usual barrier to trying it, and the current 5.26.0 release supports a modern mobile-banking starting point on iOS 9 or later. I would install it if I wanted direct Fifth Third access from my phone, but I would keep my broader budget and financial planning system separate. My practical recommendation is to use it as your secure everyday banking doorway, not as your entire financial plan.
Frequently Asked Questions
01What can I do with the Fifth Third: 53 Mobile Banking app?
Fifth Third: 53 Mobile Banking provides access to many everyday banking services from an Android or iOS device. After signing in, customers can typically review balances and transactions, transfer money between eligible accounts, deposit checks with mobile check deposit, pay bills, manage debit cards, locate branches and ATMs, and contact support. Available tools may depend on the account type, device, location, and Fifth Third’s current service offerings.
02Is the Fifth Third mobile banking app safe to use?
The app is designed with banking security features such as account authentication, encrypted connections, fraud monitoring, and options for alerts or additional verification. However, no mobile banking service can eliminate every risk. Download the application only from the official Google Play Store or Apple App Store, keep your phone and operating system updated, avoid public Wi-Fi for sensitive activity, and never share passwords, verification codes, or security answers with anyone.
03Can I deposit checks through Fifth Third: 53 Mobile Banking?
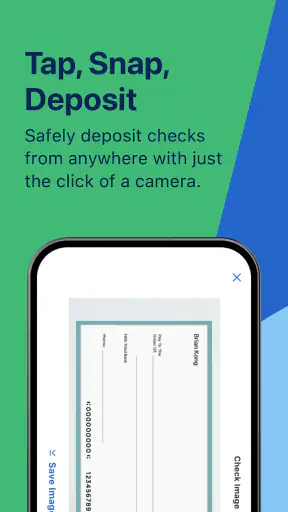
Eligible customers can generally use the app’s mobile check deposit feature by photographing the front and back of an endorsed check and submitting it for review. The images must be clear, the check must meet Fifth Third’s requirements, and deposit limits or funds-availability rules may apply. Keep the original check safely until the deposit is confirmed, then follow the bank’s instructions for retention or disposal.
04Does the app support bill payments and money transfers?
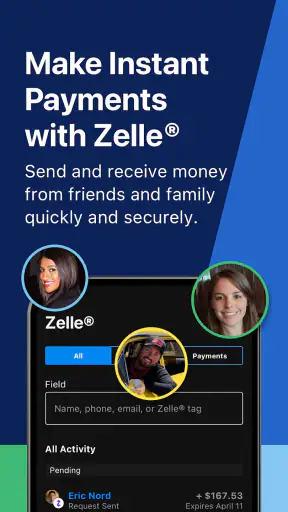
Fifth Third: 53 Mobile Banking is intended to help customers manage payments and move money without visiting a branch. Depending on your account and enrollment, you may be able to pay companies through bill pay, transfer funds between Fifth Third accounts, send money using supported person-to-person services, or make eligible external transfers. Processing times, daily limits, fees, and recipient requirements can vary, so review the confirmation details before submitting.
05What should I do if I cannot log in or notice suspicious activity?
If you cannot sign in, first verify your username, password, internet connection, and app version, then use the official recovery options rather than repeatedly guessing credentials. For a locked account or technical issue, contact Fifth Third through a verified channel, such as the number on your card or the bank’s official website. If you see an unfamiliar transaction, report it promptly, lock the affected card when available, and change compromised credentials.


